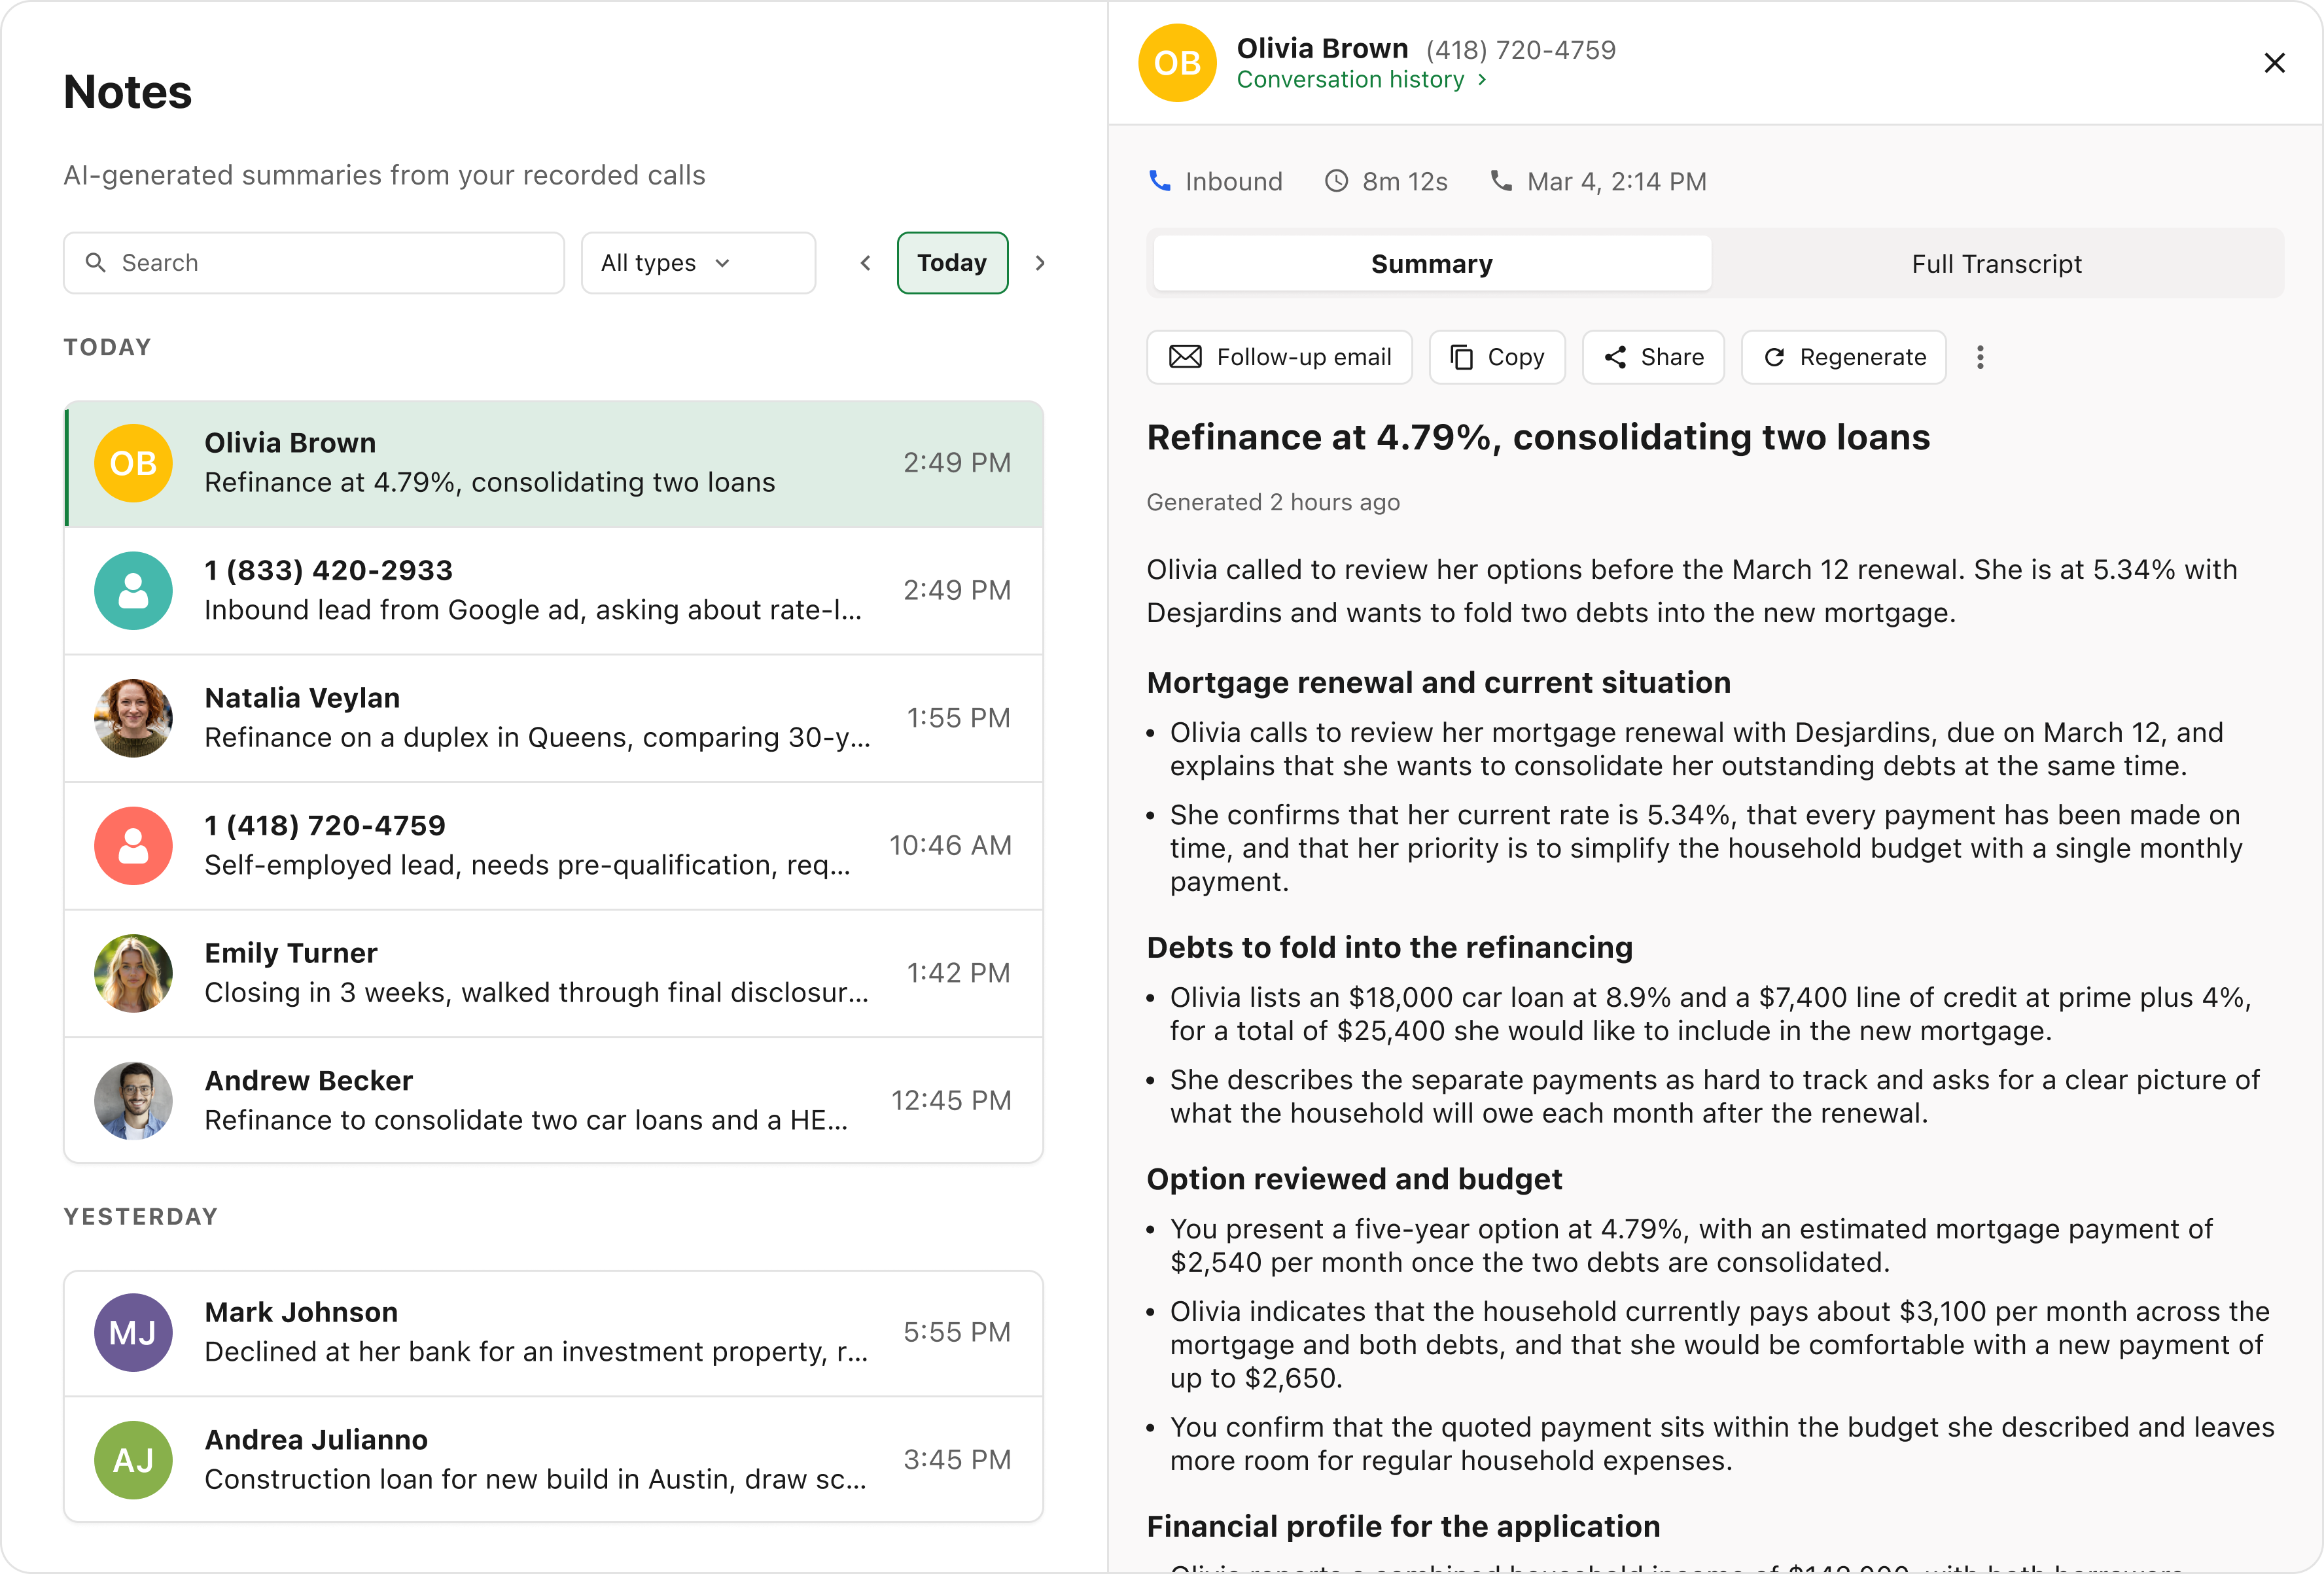
Mortgage renewal and current situation
- Olivia calls to review her mortgage renewal with Desjardins, due on March 12, and explains that she wants to consolidate her outstanding debts at the same time.
- She confirms that her current rate is 5.34%, that every payment has been made on time, and that her priority is to simplify the household budget with a single monthly payment.
Debts to fold into the refinancing
- Olivia lists an $18,000 car loan at 8.9% and a $7,400 line of credit at prime plus 4%, for a total of $25,400 she would like to include in the new mortgage.
- She describes the separate payments as hard to track and asks for a clear picture of what the household will owe each month after the renewal.
Option reviewed and budget
- You present a five-year option at 4.79%, with an estimated mortgage payment of $2,540 per month once the two debts are consolidated.
- Olivia indicates that the household currently pays about $3,100 per month across the mortgage and both debts, and that she would be comfortable with a new payment of up to $2,650.
- You confirm that the quoted payment sits within the budget she described and leaves more room for regular household expenses.
Financial profile for the application
- Olivia reports a combined household income of $142,000, with both borrowers working full time, and indicates that their credit scores are above 740.
- You note that these details will go into the application together with the income documents and the information on the outstanding loans.
Documents and follow-up
- Olivia agrees to send her T4s and car loan statement before Friday so that you can prepare the file for the lender.
- You will send a follow-up that recaps the rate and the estimated payment, confirms the documents still needed and keeps the application moving ahead of the March 12 renewal.



 Generate follow-up email



 you already know.